How to Open a Bank Account in Canada as a Newcomer (2026 Guide)
Standing in a new country without a bank account can feel like being stuck at the starting line. You can't receive your paycheque, pay rent, or start building a credit history until it's sorted, and week one already has enough on the list. The good news? Opening one is simpler than it looks. This guide covers the documents you'll need, the steps to follow, and how the major banks' newcomer programs compare.
What You'll Need Before You Walk In
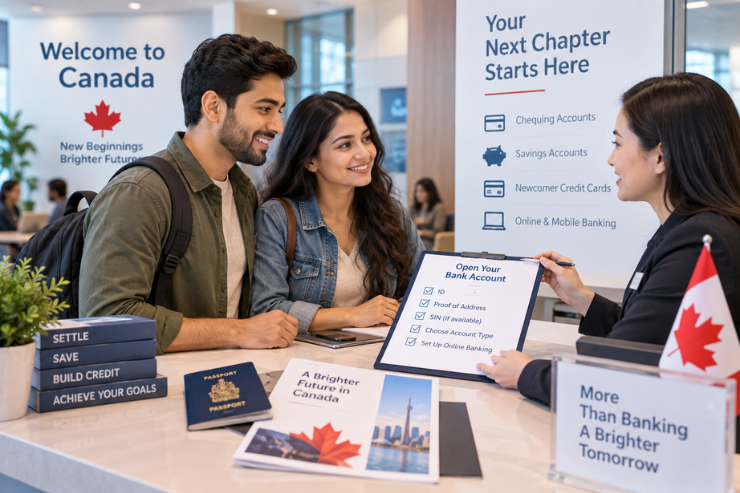
Most banks ask for a short, predictable list of documents. Having these ready before your appointment (or before you even land) saves you a second trip.
- Passport is your primary photo ID
- Confirmation of Permanent Residence (COPR), study permit, or work permit
- Proof of address in Canada and here's some good news, many banks accept a temporary or shelter address, so you don't need a permanent home lined up first
- Social Insurance Number (SIN) is helpful, but not always mandatory on day one. A number of banks will open your account and let you add your SIN once you have it
One detail worth knowing: several major banks now offer "before you land" account opening, letting you set things up online from your home country ahead of your move. It's one small piece of paperwork you can cross off before the flight, so your account is active and waiting the moment you touch down.
Step-by-Step: Opening Your Account
Step 1: Decide what type of account fits you. A chequing account handles everyday spending, a newcomer package usually bundles chequing, savings, and a starter credit card, and no-fee digital banks skip branches entirely in exchange for $0 monthly fees.
Step 2: Book an appointment, or open it online through a bank's newcomer or pre-arrival portal.
Step 3: Bring your documents. The checklist above covers what most banks ask for.
Step 4: Ask about the newcomer fee-waiver terms. How long fees are waived and what happens after that window closes, so there are no surprises later.
Step 5: Set up your debit card, Interac e-Transfer, and online banking so you can send and receive money right away.
Step 6: Ask about a newcomer credit card. Most banks bundle one that doesn't require Canadian credit history. An easy way to start your credit file early, so don't skip this step.
Canadian Banks & Newcomer Programs Compared (2026)
| Bank | Program | Fee-Free Period | Credit Card, No Canadian History Needed | Notable Perk |
| CIBC | Newcomer banking | Up to 24 months | Yes | Direct-deposit bonus; pre-arrival account opening |
| National Bank | Newcomer offer | Up to 3 years | Yes | Longest fee waiver among the Big Banks |
| Scotiabank | StartRight | 12 months | Yes | All-in-one bundle: chequing, savings, and credit card |
| TD | Newcomer package | 12 months | Yes | Extended branch hours, including evenings and weekends |
| RBC | Newcomer Advantage | 12 months | Yes | Canada's largest branch and ATM network |
| BMO | NewStart | Up to 24 months | Yes | Up to $900 cash bonus; global money transfers, safety deposit box rebate |
| Simplii/ Tangerine/ EQ Bank | No-fee digital banking | Ongoing, $0 forever | Varies | No branches, but genuinely free for life |
Note: The figures/promotions change monthly, and NSN advises checking the respective bank websites for current rates/bonus/offers.
Which One Should You Actually Choose?
There's no single "right" bank. It comes down to what matters most to you. Every newcomer program covers the basics, such as, fee waivers, a starter credit card, digital banking. Like comparing windows and blinds for a new home, the options all do the core job; it's the details that end up mattering most once you're actually living with the choice.
Here's how the details line up against a few common priorities:
- Want the longest fee-free runway? National Bank's newcomer offer can run up to 3 years, and CIBC's runs up to 24 months, the two longest waivers among the Big Banks.
- Want to bank before you land? CIBC's Smart Arrival program is built specifically for opening an account from abroad ahead of your move.
- Want in-person help near a specific city? RBC and TD have Canada's largest branch and ATM networks, which matters if you'd rather talk things through face-to-face.
- Want $0/month with no catch? A strategy some newcomers use is pairing a Big Bank newcomer account (for the fee waiver and starter credit card) with a no-fee digital account like Simplii, Tangerine, or EQ Bank, then shifting everyday banking to the digital account once the promo year ends. It's one of the more useful moves in this space, since it captures the newcomer perks up front without locking you into fees later.
These are simply how the numbers and features line up, which one fits best still comes down to your own routine, city, and priorities.
Many newcomers open a promotional account for the fee-free period and quietly switch to a no-fee digital bank once it ends. Others stick with their first bank for years simply because the branch staff made settling in easier. Both are perfectly reasonable paths, the point is that the choice is yours to revisit whenever it stops working for you.
Common Mistakes to Avoid
- Forgetting to cancel or downgrade before the fee-waiver ends. This is the #1 costly mistake newcomers make, a $15 to 17 monthly fee adds up to $180+ a year for an account you may not still need.
- Not asking about the newcomer credit card at account opening. Skipping this costs you early credit-building time.
- Assuming you need a permanent address first. As covered above, most banks accept a temporary one, so don't let it hold up your appointment.
Making the Choice That's Right for You
Learning how to open a bank account in Canada as a newcomer is one of those early wins that makes everything after it, paying rent, receiving your paycheque, building credit, a little easier. The documents are simple, the steps are predictable, and the banks themselves want your business enough to compete for it.
Whichever program catches your eye, take your time comparing the fine print before you commit. If you'd like to talk through your options with someone who's helped other newcomers navigate this exact decision, NSN's Financial Planning resources are there whenever you're ready to explore them.
Frequently Asked Questions
Q1. Can I open a Canadian bank account before I arrive?
Yes. Several major banks let you start the process online from abroad, so your account is set up and ready before you land in Canada.
Q2. Do I need a SIN to open a bank account?
Not always. Many banks will open your account without one and let you add your Social Insurance Number once it arrives by mail.
Q3. What's the difference between chequing and saving?
Chequing covers everyday spending, bill payments, and debit purchases. Savings accounts are for setting money aside and earning modest interest over time.
Q4. Is my money protected if the bank fails?
Yes. Eligible deposits at CDIC member banks are insured up to set limits, giving newcomers real peace of mind about where their money sits.
Q5. Can international students open newcomer accounts too?
Yes. Most newcomer banking programs welcome study permit holders, not only permanent residents, so students can access the same fee waivers and perks.